Fund Commentary
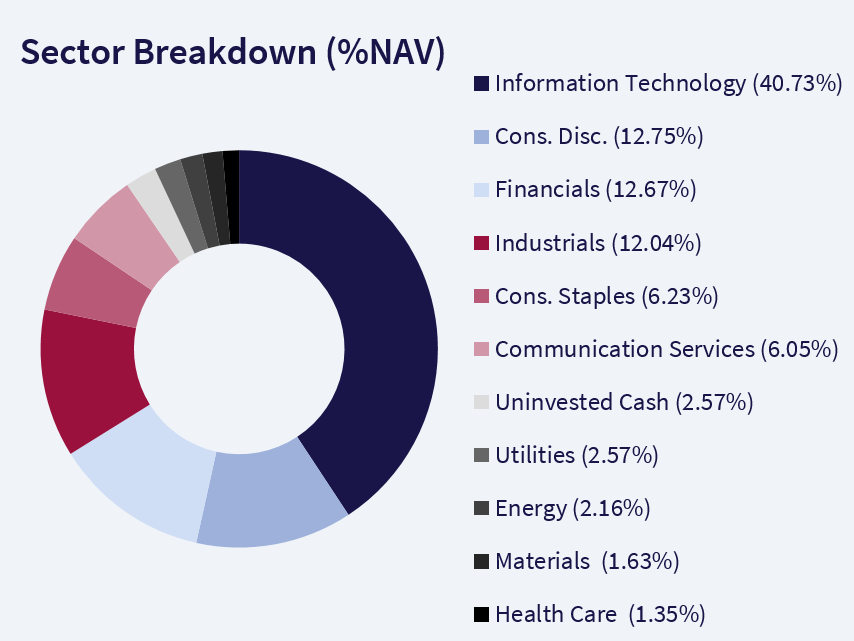
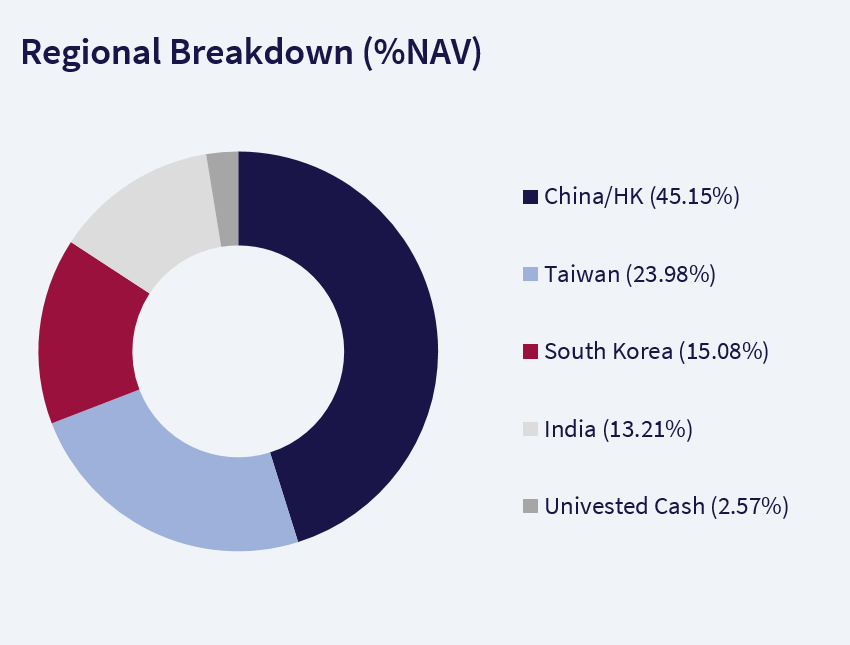
The US Dollar B share class net asset value fell 0.25% in August which compares to the 0.38% decline in the regional index. Our significant weightings in China (-3.61%), Hong Kong (-2.01%) and India (-6.62%) proved unhelpful but gains in North Asian markets (Taiwan +1.84%, South Korea +2.69%) assisted performance. By sector, information technology (+2.07%) climbed while financials (-1.94%), consumer discretionary (-7.24%) and communication services (-3.46%) were weaker.
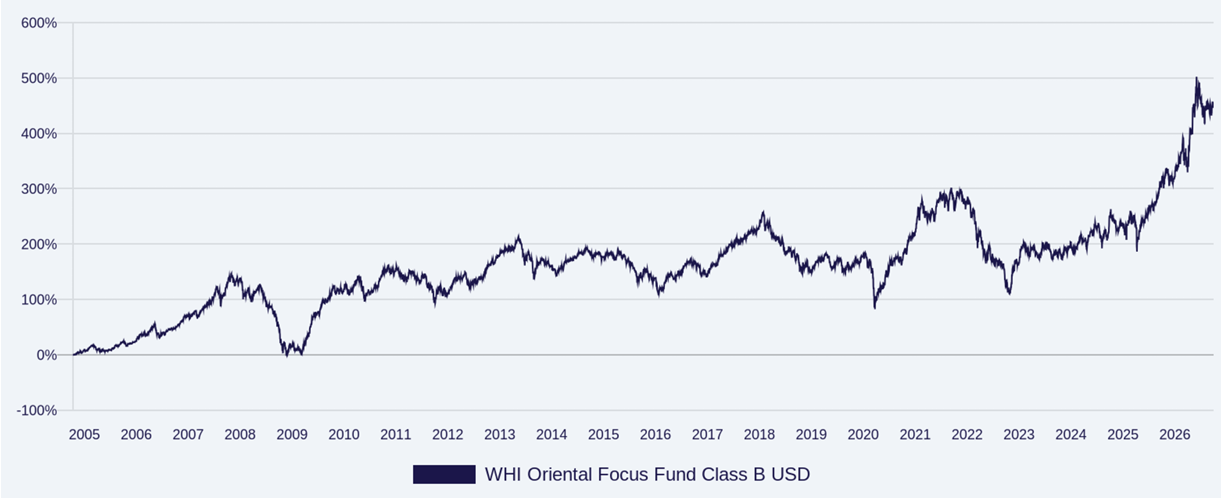
The Sterling A share class climbed 1.92% while the FE fundinfo Asia Pacific ex Japan sector fell 0.85%. Longer term performance numbers remain encouraging.
eMemory (+36.93%), JNBY (+17.65%) and Lenovo (+14.86%) made welcome gains while CATL (-19.74%), Yadea (-11.68%) and Sunny Optical (-10.99%) detracted from returns.
JNBY posted strong 2H and FY June 26 results. 2H26 revenues and net income climbed 11.6% and 12.1% respectively. This revenue growth is commendable given the lacklustre retail trends in the Chinese economy. FY26 revenues climbed 9.0% with GPM climbing from 65.6% to 66.6% while OPM rose to 22.1% from 21.5% and NPM inched higher from 16.2% to 16.5%.
The number of active members accounts climbed from 560,000 to 610,000. Membership accounts with annual purchases totalling over RMB5,000 climbed from 330,000 to 360,000. Both these metrics are useful for forecasting future revenue growth. The Board declared a final dividend 14% higher y-o-y and also declared a special dividend to celebrate the tenth anniversary of listing.
Since purchase in October 2017, JNBY has generated a compound annual return of nearly 20%. On a single digit forward PER, and with an 8% running yield, we expect this compounding to continue.
The solid growth in assets of the Fund over the past four years has seen the OCF decline from over 2% to 1.36%. 1.36% remains above industry ‘standards’ but it is a significant move in the right direction and will hopefully continue.
The third quarter earnings season will be kicked off by Samsung Electronics with ‘flash’ revenue and operating profits due imminently.
The continuing standoff in the Middle East leaves energy markets, especially diesel, in disarray although there have been some signs of increased shipments of late. It seems unlikely that Iran will wish to end the conflict ahead of the November elections in the USA. Any sign of progress after that date may well support the Indian subcontinent and ASEAN markets which have been the obvious losers since the conflict started.
Monthly data as at: 30/09/2026.