Fund Commentary
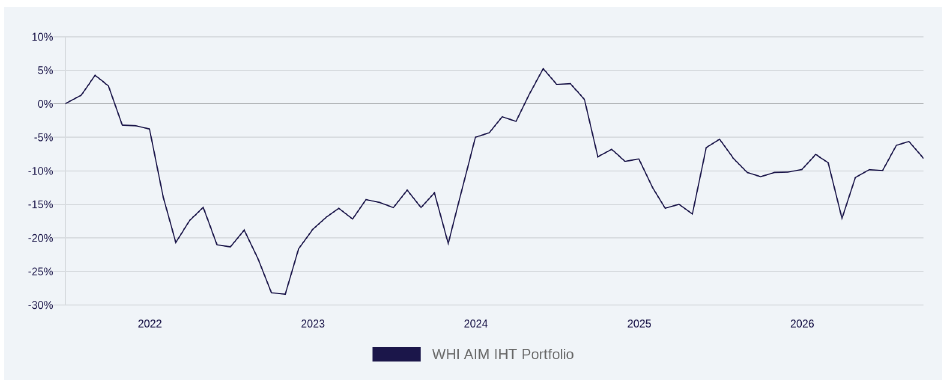
The WH Ireland AIM MPS declined 2.68% in September 2026. All figures are presented in GBP.
UK equities declined amid a challenging macroeconomic backdrop, with persistent inflation, elevated government bond yields and interest rate uncertainty weighing on investor sentiment. Higher energy prices and renewed geopolitical tensions in the Middle East added to inflationary concerns, while smaller companies remained particularly sensitive to borrowing costs and growth expectations.
Despite the challenging environment, the portfolio marginally outperformed the broader UK AIM equity market, reflecting the resilience of its long term holdings in high quality businesses.
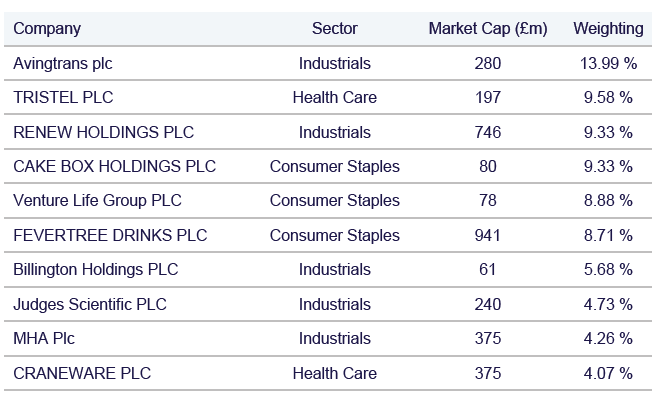
Billington, Avingtrans and RWS Holdings were the strongest relative contributors, while Boohoo also recorded double digit gains. However, these contributions were insufficient to offset weakness in Judges Scientific, Cake Box and Craneware, resulting in a negative absolute return.
Billington delivered strong first half results, with revenue increasing 29.1% to £53.95m, EBITDA rising 39.2% to £3.73m and profit before tax increasing 70.1% to £2.84m, driven by an improved project mix and operational efficiencies. Structural Steelwork remained the key growth driver, while a record order book provides visibility into 2027 and 2028, supported by demand across energy, data centres and infrastructure. Cash declined to £12.62m due to working capital requirements and contract timing. Management expects FY26 results to remain in line with market expectations despite competitive conditions.
Avingtrans delivered a strong FY26 performance, with revenue increasing 4.4% to a record £163.3m and adjusted EBITDA rising 24.0% to £20.7m. Improved gross margins and operating leverage drove adjusted profit before tax up 45.3% to £12.5m, while adjusted diluted EPS increased to 31.3p. The Energy division remained the principal growth driver, benefiting from demand for data centre infrastructure, nuclear power and electrification, alongside further contract wins. The Medical division progressed towards commercialisation, with Adaptix securing regulatory approvals and its first material non destructive testing contract, while operating losses narrowed. Net debt declined to £11.8m, and a subsequent £20m net placing will support Hayward Tyler’s capacity expansion. Management reported a positive start to FY27, with momentum continuing across both divisions.
Judges Scientific reported a weak first half, with revenue declining 21% to £55.7m and adjusted profit before tax falling 75% to £3.2m, reflecting reduced US research funding, delays in China and continued weakness in offshore wind. Adjusted EPS decreased 72% to 39.0p, while operating cash generation fell to £4.3m. Despite these challenges, eight businesses delivered growth, supported by healthier conditions in semiconductors and battery development, alongside cost control initiatives. Order intake improved significantly in early H2, reaching just 1% below the prior year to date level, while the order book remained broadly stable. Management maintained FY26 guidance in line with market expectations, although end market uncertainty and the absence of a Geotek coring expedition in 2027 remain headwinds.
While near term uncertainty persists, attractive valuations and resilient, high quality businesses offer compelling long term opportunities. We remain focused on identifying mispriced compounders with durable competitive advantages and strong cash generation, positioning the portfolio to capture upside as conditions improve while protecting capital against permanent loss.
Monthly data as at: 30/09/2026.