For professional clients only. The information contained within this post is not intended for retail clients.
This article updates previous articles published over the last few years which highlight the underlying profitability of the portfolio holdings in the Fund. The profitability data was sourced from Bloomberg on 28 August 2026.
Profitability
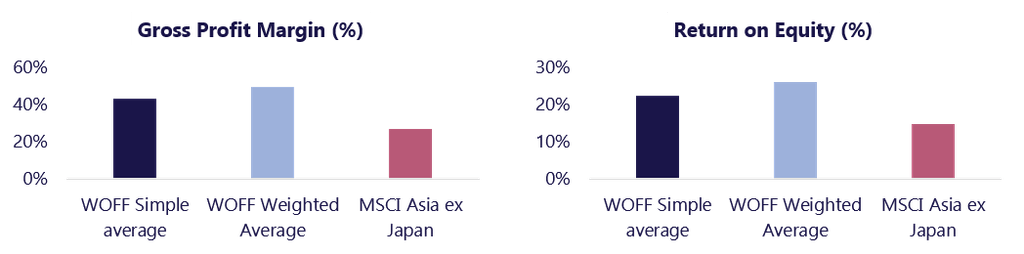
The two charts above confirm the vastly superior profitability of the Fund’s portfolio compared to the Asian market. The weighted average return on equity of the portfolio stands at 25.97%, almost double the 14.73% return on equity of the regional index, MSCI Asia ex Japan, while the Fund’s weighted gross profit margin stands at 49.28%. This is almost double that of the index.
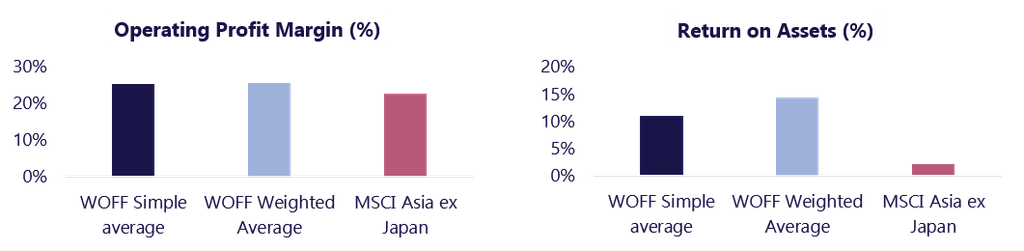
Unsurprisingly this superior profitability is evident in other profitability metrics such as operating profit margins and return on assets. The Fund’s weighted operating profit margin of 25.47% is higher than that of the market (22.42%) while the return on assets, at 14.39%, is almost seven times higher than that of the index.
The fact that the simple average of these metrics for the portfolio are a little lower than the weighted average confirms that our larger, higher conviction, holdings have a superior profitability profile. This is as one would expect.
The top ten holdings account for some 55% of the portfolio while the average holding period for these ten stocks stands at over eight years. We are happy to ride the inevitable market cycles as long as the profitability metrics illustrated above remain highly competitive. The chart below illustrates the compound growth rate of the top ten holdings relative to the regional index since purchase to 28 August 2026.
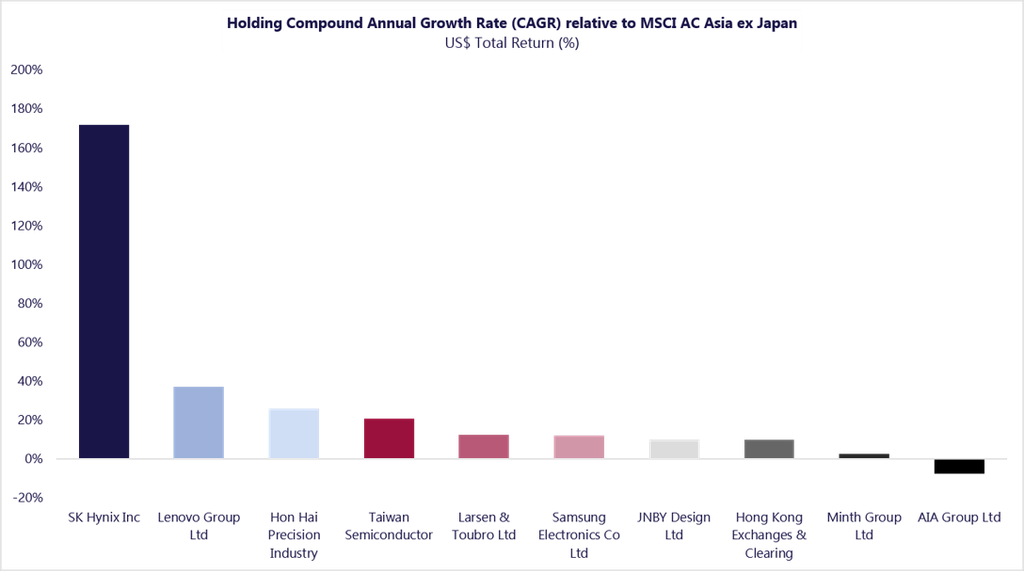
Of the top ten positions, only AIA Group Ltd has failed to beat the index, albeit by a small margin.
Investing in highly profitable and fast-growing companies does, unfortunately, come at a cost. In our last paper we noted that the portfolio holdings traded at a premium to the regional index on a price to earnings ratio comparison. This continues to be the case, the portfolio is trading on circa 23x forward earnings while the regional index’s price earnings ratio stands at 17x. We continue to believe that paying up for quality growth stocks remains the best way to generate strong long term performance.
Earnings Growth
According to a recent Bloomberg report, earnings estimates for Emerging Market companies are rising at the fastest pace on record. As we have noted previously, the Asia ex Japan universe and the Emerging Market universe are essentially twins – both dominated by Taiwan, South Korea and China. These three markets account for 77% of the Asia ex Japan universe and 69% of the Emerging Market economy.
Unsurprisingly it is the earnings profiles of TSMC, Samsung Electronics and SK Hynix (31.1% of Asia ex index and 27.8% of the EM index) which is driving these upward revisions. Investors in these two asset classes need to understand that any downturn in the AI driven demand for advanced chips would quickly reverse this earning growth.
Conclusion
The WHI Oriental Focus Fund is, per se, not a cheap portfolio. The important difference is that WOFF’s portfolio is compounding at a rate that is far superior to that of the Asian universe.
It is also noteworthy that, in aggregate, the Fund’s portfolio remains debt free.
The A share class is rated second quartile over six months, one year, two years and three years by FE fundinfo as at 28 August 2026. We are confident that we can repeat this performance over the next few years.
The strong performance over the past few years has also positively impacted the OCF ratio which has fallen from over 2% to 1.36%.
Henry Thornton
Fund Manager, WHI Markets Oriental Focus Fund
Important Information
WHI Oriental Focus Fund (the “Fund”) is a sub-fund of EPIC Funds p.l.c. (the “Company”), which is an open-ended umbrella fund authorised in Ireland as a UCITS fund and regulated by the Central Bank of Ireland. Compensation will not generally be available to UK investors under the Financial Services Compensation Scheme. The Fund is, however, a recognised collective investment scheme within the meaning of section 264 of the UK Financial Services and Markets Act 2000 and shares in the Company may therefore be promoted to the UK public by persons authorised to carry on investment business in the UK. Distribution of this material and the offer of the Fund are specifically restricted in certain jurisdictions. In particular, but without limitation, neither this material nor shares in the Fund are available to US persons.
This document is for general information purposes only and does not take into account the specific investment objectives, financial situation or particular needs of any particular person. It is not a personal recommendation, and it should not be regarded as a solicitation or an offer to buy or sell any shares in the Fund. This document represents the views of WH Ireland at the time of writing. It should not be construed as investment advice. Any person interested in investing in the Fund should conduct their own investigation and analysis of the Fund and should consult their own professional tax, accounting or other advisers as to the risks involved in making such an investment. Full details of the Fund’s investment objectives, investment policy and risks are set out in the Fund’s Prospectus and Supplement which, together with the Key Investor Information Document (“KIID”), are available on request and free of charge from EPIC Investment Partners (Ireland) Limited, 1H The Atrium, Cork, T23 T2VY, Ireland and, in the UK, from WH Ireland Limited, 16–18 Hatton Garden, London, EC1N 8AT. Any offering of the Fund is only made on the terms of the current Prospectus, Supplement and KIID. A subscription in the Fund can only be made after the provision of the KIID and should be made solely upon the information contained in the Prospectus, Supplement and KIID.
An investment in the Fund is not suitable for an investor who cannot sustain a loss on their investment. There is no guarantee of the Fund’s future performance and past performance is not a reliable indicator of future performance. The value of your investment and the income derived from it can go down as well as up, and you may not get back the money you invested. The risks associated with making an investment in the Fund are described in the Prospectus and Supplement but investors should note, in particular, the following: 1) Foreign currency denominated investments are subject to fluctuations in exchange rates that could have a positive or an adverse effect on an investor’s returns. There is also a risk that currency hedging transactions for one share class may in extreme cases adversely affect the net asset value of the other share classes within the same sub-fund since there is no legal segregation between share classes; 2) The Fund is subject to the risk of the insolvency of its counterparties; and 3) Emerging market securities are subject to greater social, political, regulatory, and currency risks than developed market securities. This may impact the liquidity and value of such securities and, consequently, the value of the Fund.